
Sheet A-01 / Apartment lending
Apartment Loans Parramatta
Apartment loans Parramatta are approved on the building at least as much as on the borrower. Your income can be immaculate and the loan still fail, because the lender assessed the unit, decided it did not want that risk, and is not obliged to tell you which part of it was the problem.
Here that is the normal case rather than the edge case, and it changes the order you should do things in. The building question is cheap to answer while you are still deciding what to bid on and expensive to answer once you have signed. That is the whole argument for asking it early.
What We Check on Your Building Before You Offer
Give us a Parramatta address and a floor plan and we run the unit against lender policy: internal size, the postcode, how many apartments sit in the development, whether the lender still has room in that block, and how the building is classified. What comes back is the list of lenders that will fund it, the deposit each one wants, and anything that would stop an approval.
That is a different job from a pre-approval. A pre-approval tests you. It says nothing about the property, and lenders only order a valuation after contracts are exchanged, so the building assessment usually lands at the worst possible moment. Doing it first is the whole point.
You will reach us at one of three points: before making an offer, after a bank has declined a unit without explaining why, or holding a pre-approval and wanting to know which Parramatta buildings it will actually stretch to.
What Happens When You Call Us About a Unit
The order below front-loads the property checks, because on an apartment those are what fail. Nothing needs you in an office and nothing is lodged until you have seen what came back.
-
You tell us the building
The Parramatta address, and the floor plan if the agent has sent one. Five minutes on the phone. If you are still browsing rather than bidding, a listing link does the same job.
-
We run it across the panel
Internal area against each lender’s minimum, the postcode against their density rules, the development against their exposure limits. You get the lenders that will fund it and the ones that will not, with the reason in each case.
-
You find out what deposit it needs
Policy on a specific unit sets your loan-to-value ceiling, and that ceiling sets your deposit. On a small unit in a large tower the number can sit a long way from the one you had budgeted, which is worth knowing before you bid rather than after.
-
We take it through to settlement
We lodge with the lender whose policy fits the building, manage the valuation and the questions that come back from the assessor, and keep your conveyancer in step with the finance dates.
Useful to have to hand: the listing or the address, the floor plan with the internal area marked, your deposit figure and your credit card limits. If all you have is an address, that is enough for a useful answer.
What You Will Want to Ask Us First
How quickly can you tell me whether a building is a problem?
Usually inside the same conversation for the obvious things. The internal area off the floor plan, whether the postcode carries density rules and whether the development is large enough to trigger them are all checks we can run while you are on the phone.
Confirming that a particular lender still has room in that block takes longer, because it means asking them. If you are bidding at a Parramatta auction on the weekend, tell us which day and we will work to it.
What does it cost me to have a building checked?
Nothing, and there is no limit on how many you check. The lender pays us a commission when a loan settles, which is how broking is paid for in Australia, so the assessment costs you the same whether you buy the unit or walk away from it.
If a fee ever applied to your circumstances, it would be in writing in our Credit Guide before you decided whether to go ahead.
Why not just ask my own bank about the apartment?
You can, and you will get an accurate answer about one lender. The difficulty is that the answer is binary and you learn nothing from it: a decline tells you that bank will not fund the unit, not whether any of the others will.
Because we place these across a panel of more than 35 lenders, a no from one is the start of the search rather than the end of it. That is most of what we are for on an apartment.
What do you actually do once I have made an offer?
We lodge with the lender whose policy suits the building, order and manage the valuation, answer the assessor’s questions and keep your conveyancer in step with the finance dates.
On a unit the valuation is the part worth watching, because a valuer who reads the building conservatively can move your deposit late. We would rather see that coming than explain it afterwards.
Whether a Bank Will Lend on Your Parramatta Apartment
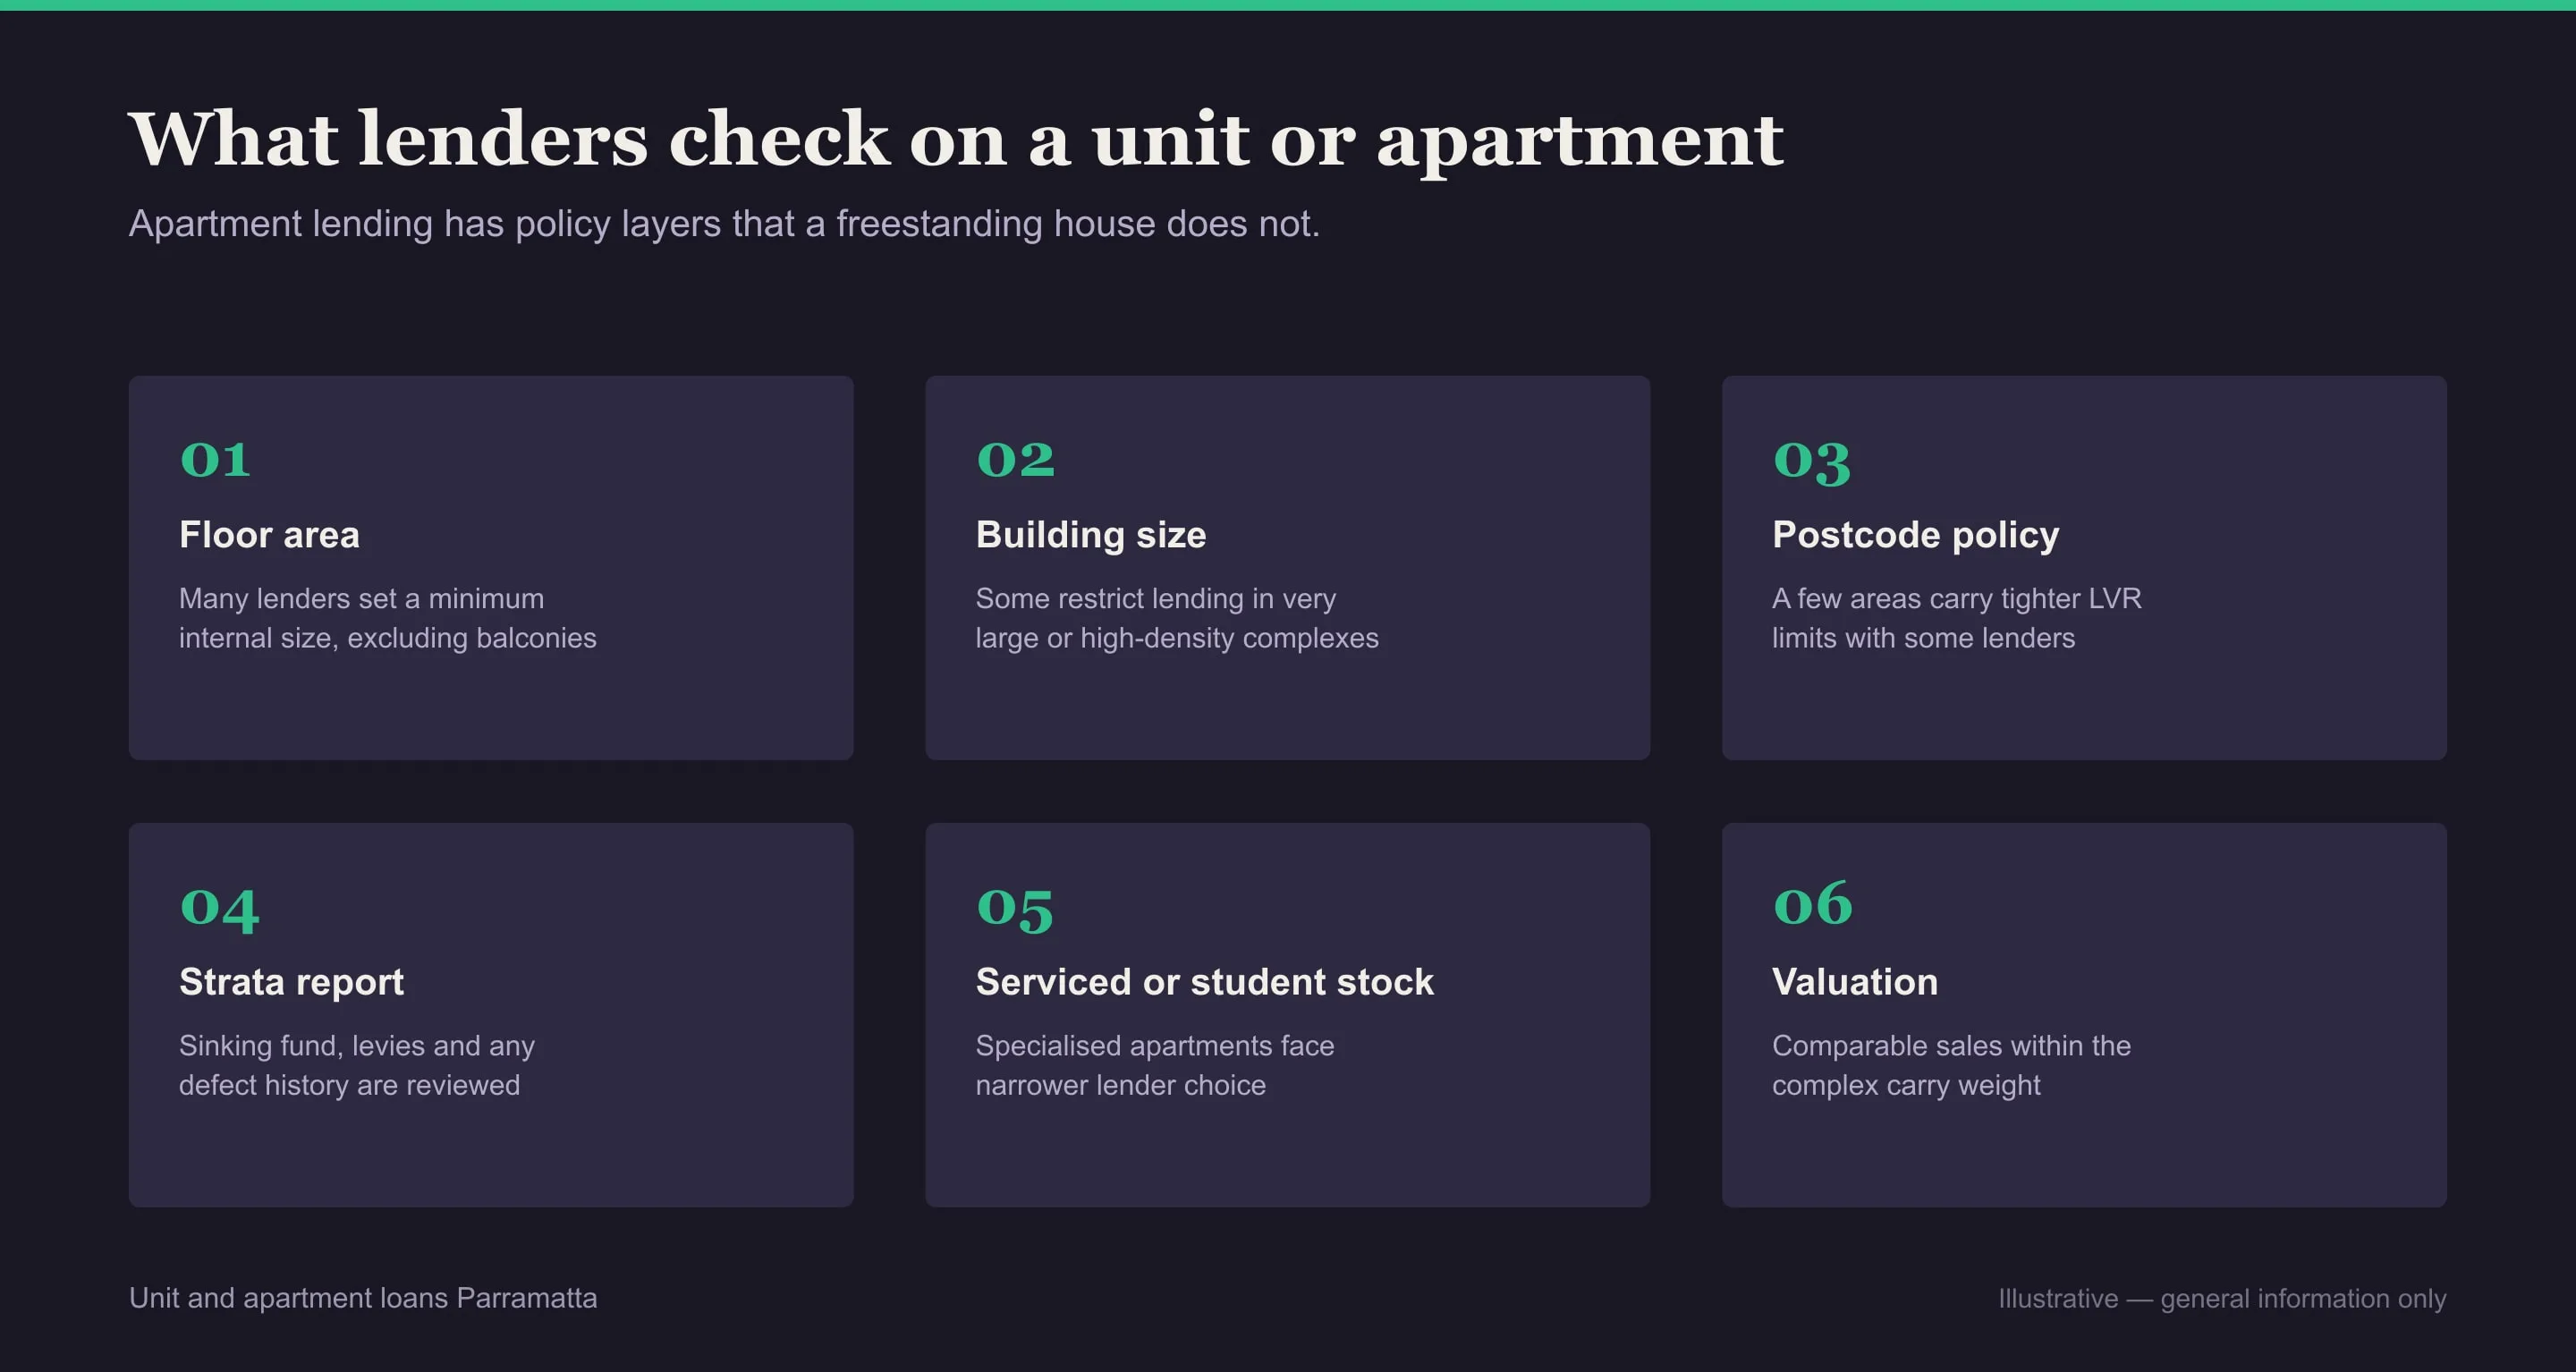
Most lenders want at least about 50sqm of internal living area before they will lend at a standard deposit. Internal is the word doing the work: the balcony and the car space are excluded, so a Parramatta unit advertised at 62sqm can measure 48sqm on the part the lender counts. That is why we ask for the floor plan rather than the listing.
Some lenders go smaller. Teachers Mutual and its subsidiaries accept 35sqm on a studio or one bedroom, and Yard accepts 35sqm internal. Below 40sqm you are generally capped at 80% of the value, because the mortgage insurers will not cover a unit that small and most lenders will not go past 80% without insurance. So a 38sqm studio is financeable, but it needs a 20% deposit rather than the 10% you may have planned for.
What we do with that is simple. We measure the internal area off the plan, match it to the lenders whose minimum it clears, and tell you the deposit each one implies. Where a unit sits just under a threshold, it is worth knowing that a different lender starts 15sqm lower.
When Your Postcode Caps What You Can Borrow
Lenders keep lists of postcodes where they consider apartment supply heavy, and they lend more conservatively inside them. Parramatta and Harris Park (2150), Granville and Rosehill (2142) and Westmead (2145) all appear on Granite Home Loans’ published Security Postcode Matrix from October 2024, where a strata apartment in a development of more than 100 units is capped at 90% and the lender limits itself to roughly 10% of the development.
Two cautions on that, because it is the part most often repeated wrongly. Granite is one lender, and the thresholds move: an earlier version of the same matrix used a 30-apartment trigger and an 80% cap. The major banks maintain equivalent lists and do not publish them, so nobody can honestly hand you a definitive restricted-postcode list and call it the market. What we can do is put your specific Parramatta address to the panel and report what comes back.
The practical consequence is that your deposit is not a fixed number you carry from building to building. The unit sets it. We would rather size it against a real Parramatta address than a rule of thumb.
When the Building Is the Problem, Not You
A lender can decline your loan on a unit it would have funded last month, because it has reached its exposure limit inside that development. Nothing about your file changed. It is a portfolio decision and there is no appeal, which is why a strong borrower with a clean application still gets a surprise.
Three other classifications quietly reduce or remove lender appetite. A studio with no separate bedroom is treated as harder to resell. A building with communal laundries rather than in-unit facilities reads as older stock or student accommodation. And a unit that is or has been run as a serviced or short-stay apartment is a different product to most credit teams, whatever it looks like on inspection.
None of those are visible from a listing and none of them are your fault. We check them before you commit, and where the Parramatta building is the obstacle we go looking for the lender whose policy still fits rather than telling you to find another apartment.
What It Costs to Arrange Apartment Loans Parramatta
Nothing. We are paid a commission by the lender when a loan settles, so the assessment, the policy check and the lender shortlist cost you the same whether or not you end up buying that unit. If a fee ever applied to your situation, it would be set out in writing in our Credit Guide before you decided whether to go ahead.
That matters more here than on most finance, because you may want three or four Parramatta buildings checked before one of them works out. There is no meter running on that, and there is no sensible version of this job where you pay by the address.
How Lenders Read a Building
Why did my bank decline an apartment my friend got approved on?
Almost always because the two of you went to different lenders, and apartment policy is where lenders differ most. One may cap its lending in developments over 100 units, another over 30, and a third may simply have reached its exposure ceiling in that block.
It is rarely a comment on your application. The identical file regularly gets approved by the next lender along, and finding that lender is the work.
Is there a minimum apartment size for a loan?
Effectively yes, though each lender sets its own rather than it being law. About 50sqm of internal living area is the common threshold for lending at a standard deposit, and some lenders accept 35sqm on studios and one-bedroom units.
Under 40sqm internal you are generally limited to 80% of the value, because mortgage insurers will not cover units that small. The unit is still financeable. It just needs a larger deposit than you may have been planning for.
What makes a postcode count as high density?
Two things together: the postcode appears on a lender’s own list, and the specific development is large enough to trip the rule. On the Granite matrix that means a strata apartment in a development of more than 100 units, which caps the loan at 90% and limits that lender to roughly 10% of the block.
Thresholds differ between lenders and change over time, and the major banks do not publish theirs at all. Treat any list you find online as one lender’s position rather than the market’s.
Does a pre-approval mean I can buy any unit I like?
No, and this is the misunderstanding that costs people the most. A pre-approval assesses you: your income, your deposit and your commitments. It says nothing about the property, and the lender does not look at the building until after contracts are exchanged.
So a pre-approved buyer can still be declined on a specific apartment. Running the building check first is what closes that gap, and it is why we ask for an address as early as you have one.
Do apartment loans Parramatta need a bigger deposit than a house loan?
Sometimes, and the reason is the property rather than you. If the unit is small, or the building is large and sits in a listed postcode, the loan-to-value ceiling drops, and a lower ceiling means more cash from you.
Where mortgage insurance is triggered it is usually added to the loan, so the difference shows up in what you borrow rather than as a separate bill. We work the numbers on the specific unit so you can compare it properly against anything else you are looking at.
Who Checks Your Building for You
The person who answers the phone is the person who reads the floor plan and puts the address to the panel. It does not go to a processing desk, which matters when an agent wants an answer before Saturday.
We do enough of these in Parramatta to know which lenders have been comfortable in which buildings lately, and that is knowledge with a shelf life. It comes from working one market rather than from reading a policy document.
- Phone (02) 7813 2050
Quickest if you have a property in front of you and a question about it.
- Form Use the enquiry form
Better if you are on site or at work and cannot take a call back.
- Email info@mortgagebrokerparramatta.au
Suits a contract, a floor plan or a loan statement you want read.
Parramatta NSW 2150. Monday to Friday, 9am to 5pm.
Get the Building Checked First
Give us a Parramatta address and we will tell you which lenders will fund it, what deposit each of them wants, and whether anything about the block would stop an approval. It is a short conversation, and it is the one that decides how the rest of the purchase goes.
Where We Work
- Business
- Mortgage Broker Parramatta
- Location
- Parramatta NSW 2150
- Phone
- (02) 7813 2050
- info@mortgagebrokerparramatta.au
- Hours
- Monday to Friday, 9am to 5pm