
A-03 / Deposits, schemes and thresholds
First Home Buyer Loans Parramatta
The median unit in Parramatta is around $620,000, which puts most first home buyer loans Parramatta comfortably inside the federal scheme caps rather than fighting them. That is not the position national coverage assumes you are in, and it changes what the conversation is about.
It stops being whether the property qualifies on price and becomes which help you can actually stack on it, and whether the lender you want takes part in the scheme you need. Both answers move with the address, so they are worth having against a real one before you start making offers.
What We Sort Out for Your First Purchase
Three separate things get confused constantly, so it is worth separating them. The 5% Deposit Scheme is a federal guarantee that lets you buy with a smaller deposit and no lenders mortgage insurance. The First Home Buyers Assistance Scheme is NSW transfer duty relief. The First Home Owner Grant is a cash payment, and only on new homes. They have different rules, different thresholds and different administrators.
Our job is to tell you which of them you qualify for, what each is worth in your case, and how they stack together on the purchase you are actually contemplating. Then we place the loan with a lender that participates in the scheme you are using, because not every lender does.
What that adds up to is a deposit figure and a purchase price you can trust, worked at the rate lenders assess you on rather than the rate you would pay.
Buying Your First Place in Parramatta, Start to Keys
Nothing here needs an appointment in an office and nothing gets lodged until you have seen the numbers and decided. The first conversation is short.
-
A first call, about twenty minutes
What you earn, what you have saved, whether anyone is helping, and what you are hoping to buy in Parramatta. That is enough for a rough borrowing figure and a straight answer on which schemes are in play.
-
You get the real numbers
Your borrowing capacity assessed the way a lender does it, your deposit against each scheme threshold, and the duty position on the Parramatta price range you are looking at. If the answer is that waiting three months puts you in a materially better place, we will say so.
-
Pre-approval with a Parramatta lender that participates
We lodge with a lender whose policy suits your income and, where you are using the guarantee, one that takes part in the scheme. You go to Parramatta inspections knowing what you can bid rather than guessing at it.
-
Offer, approval and settlement
Once you have a property we convert the pre-approval, manage the valuation and the assessor’s questions, and keep your conveyancer in step. You get told where it is up to instead of having to chase it.
Useful to have to hand: your last few payslips, a rough savings figure, your credit card and buy-now-pay-later limits, and any HECS balance. None of it is needed for the first call.
What You Will Want to Ask Us First
How soon can you tell me which schemes I qualify for?
In the first conversation. The tests are eligibility rules rather than credit decisions, so whether you are a first home buyer, whether the price sits under each threshold and whether you intend to live there are all answerable on the phone.
What takes longer is a pre-approval, because that is a lender assessing you properly rather than us reading a rule. That is a matter of days rather than weeks in most cases.
Who pays you, and does it cost me anything?
It costs you nothing. The lender pays us a commission when the loan settles, and it does not come out of your deposit or your Parramatta loan. Nothing is added to what you borrow and nothing is deducted from what you have saved.
If a fee ever applied to your circumstances, it would be set out in writing in our Credit Guide before you decided whether to go ahead. That is the point of the Credit Guide.
What happens if I cannot borrow enough yet?
Then we say so, and we tell you what would change it. Usually it is something specific: a credit card limit that counts against you at its limit rather than its balance, a car loan with a year left, or savings that need to sit still for three months to count.
Coming back in six months with those handled puts you in a far better position than being talked into stretching. We would rather have that conversation than the wrong first one.
Do I have to come into an office?
No. Most of it happens by phone and email, and documents are signed electronically. People buying their first place are usually working full time, and losing a morning to an appointment is not a good use of it.
If you would rather sit down with someone, we will arrange it in Parramatta. It is just not a requirement.
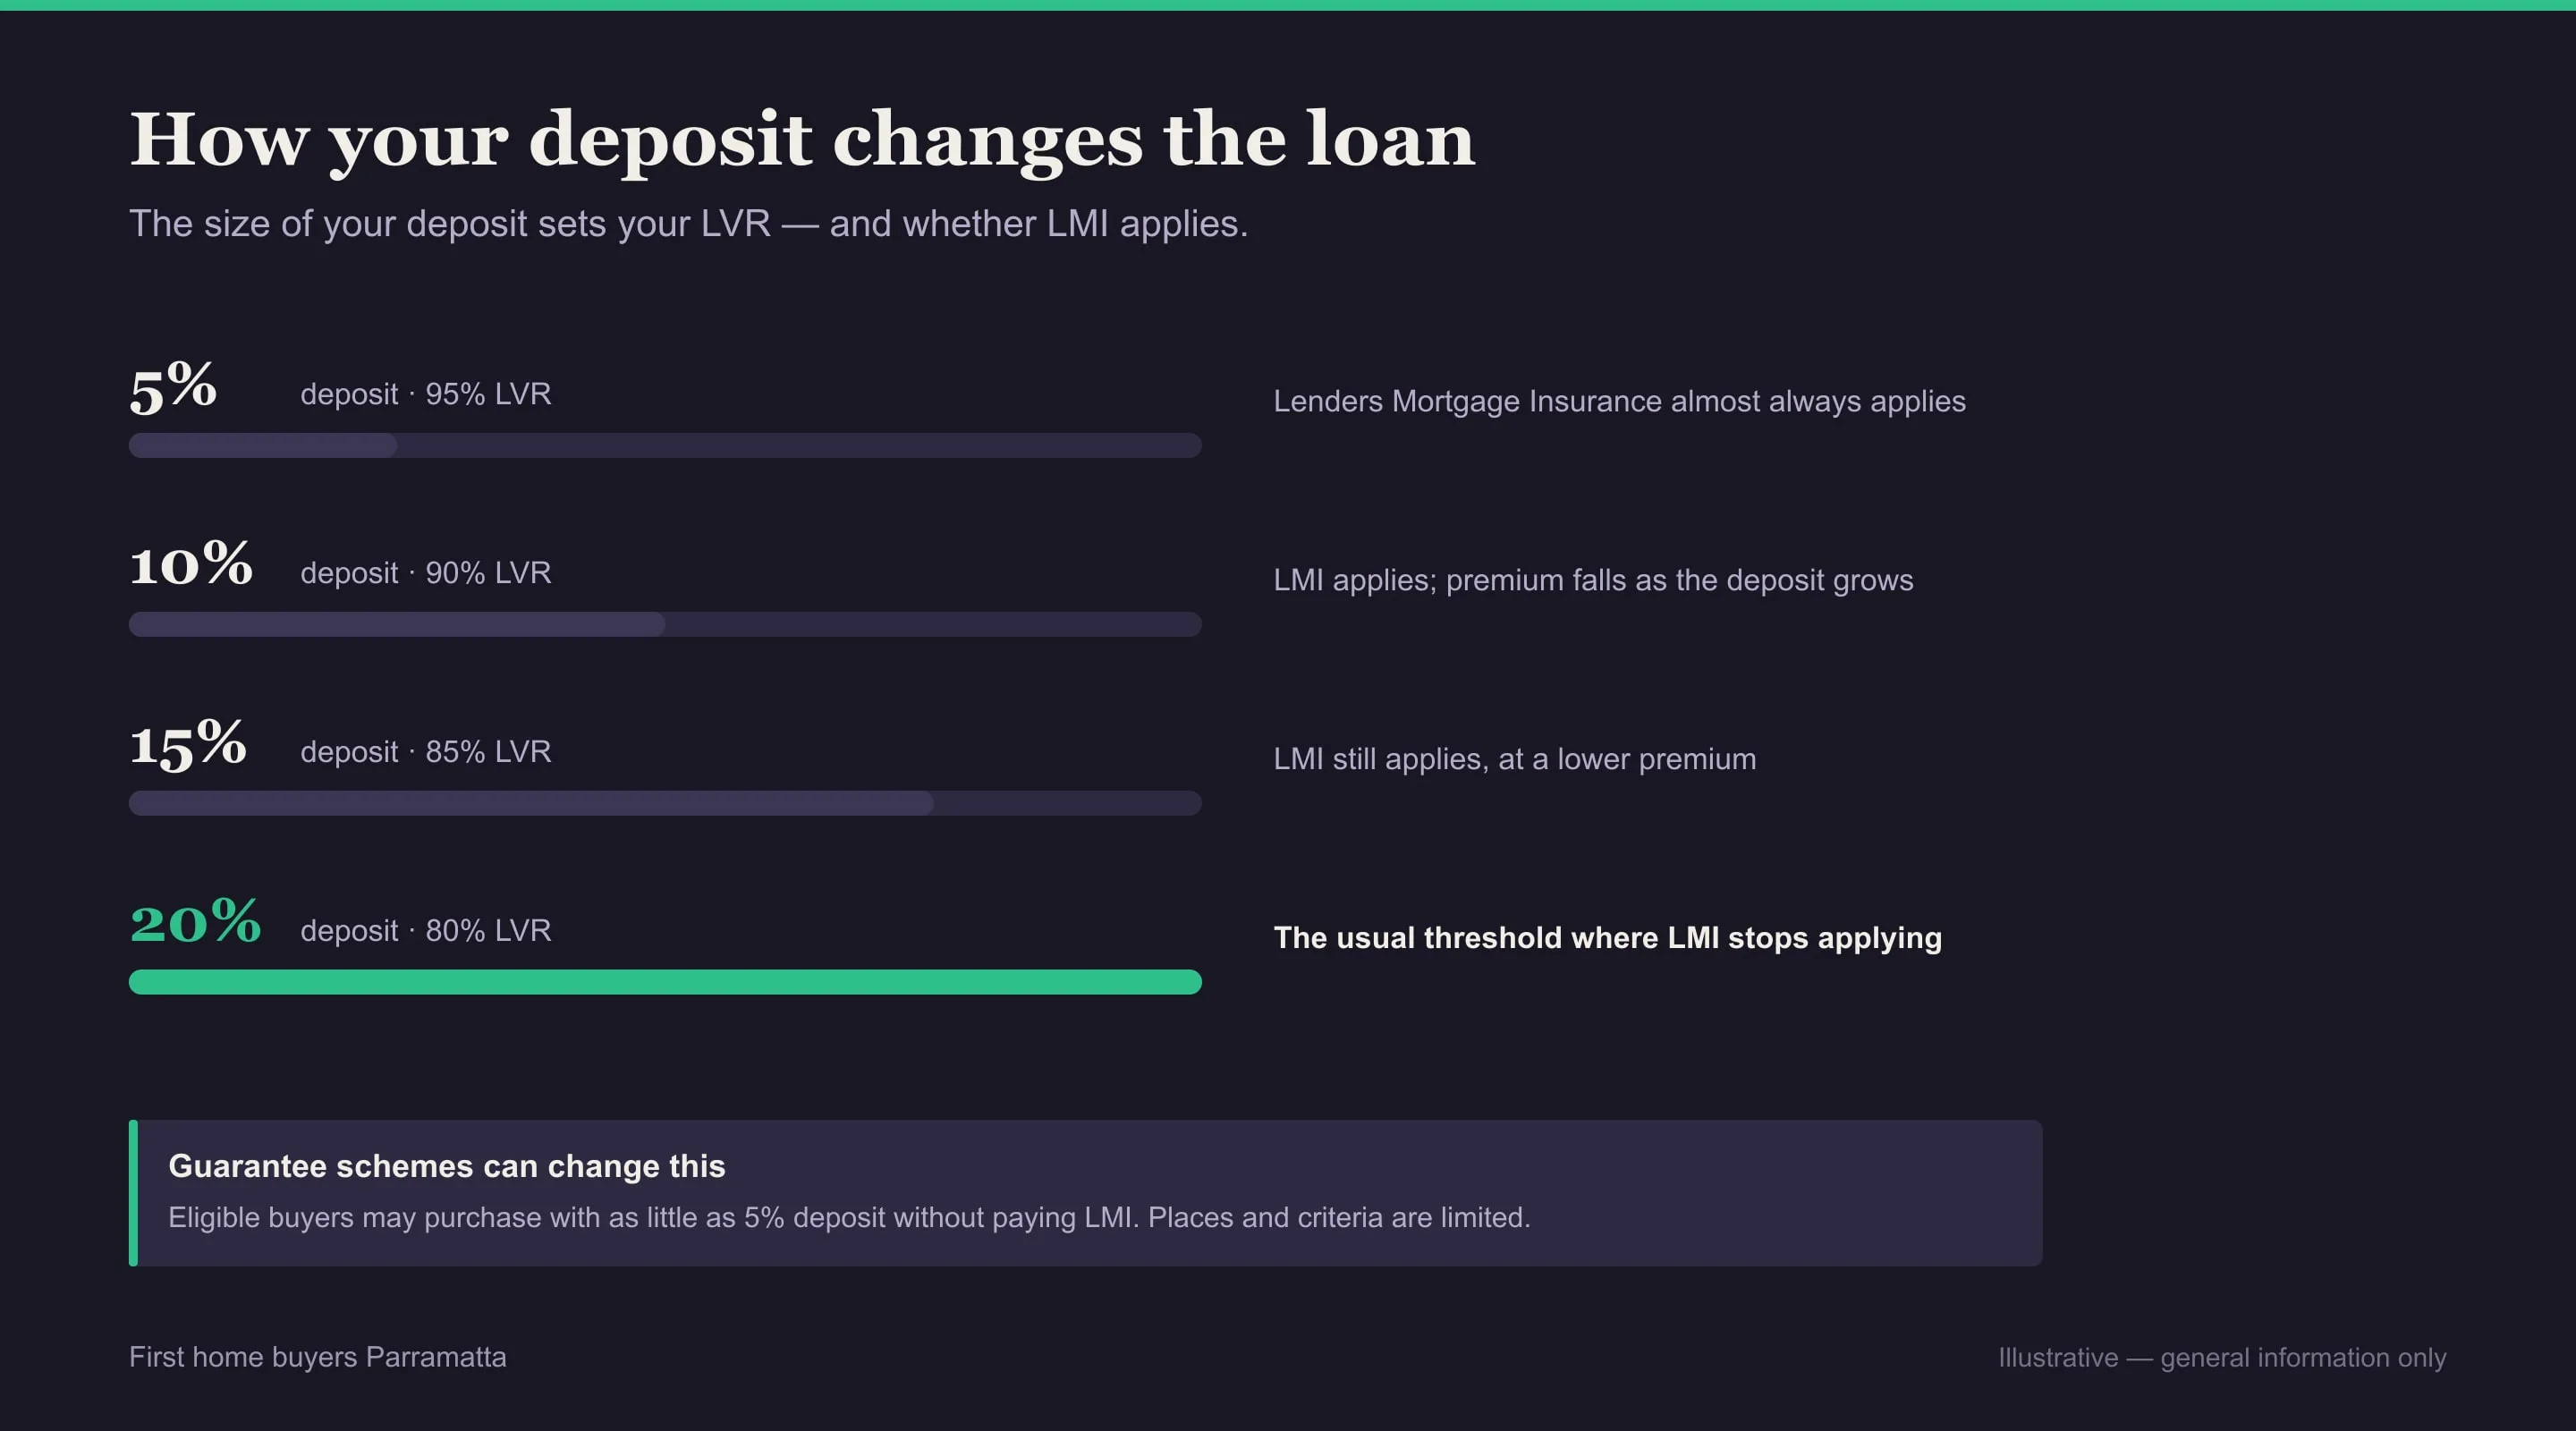
How Far a Deposit Goes on First Home Buyer Loans Parramatta
From 1 October 2025 the federal scheme changed shape. The income caps came off, the annual limit on places came off, and the property price cap for Sydney went to $1,500,000. Australian citizens and permanent residents can both use it.
It is a guarantee, not a grant. No money is paid to you. The government guarantees part of the loan so the lender does not require you to hold a twenty per cent deposit and does not charge lenders mortgage insurance. You still borrow the full amount and you still repay it. What you save is the insurance premium and the years spent saving the rest of the deposit.
Two practical points. The cap applies to the property, and the government publishes a tool for checking which postcodes fall into which cap, so the answer for a specific address is knowable rather than a matter of opinion. And not every lender participates, which means the scheme quietly narrows your lender choice at the same time as it widens your buying power. We work with that rather than around it.
NSW Duty Relief and the Thresholds That Set It
The First Home Buyers Assistance Scheme removes transfer duty entirely on a first home valued up to $800,000, and reduces it on a sliding scale between $800,000 and $1,000,000. On vacant land the full exemption runs to $350,000 with a concession up to $450,000. Above the top of each band, duty is payable in full.
Those thresholds have a hard edge, and it is where a lot of money moves. A purchase agreed just over $800,000 is not slightly worse off than one just under it. The difference at that line is large enough to be worth knowing before you make an offer, because it is the sort of thing that a few thousand dollars of negotiation can decide.
There is a residence requirement attached: you have to move in within the required period and live there for the required time. It is not a rule you can plan to ignore and it does not fit every buyer, particularly anyone intending to rent the place out. We check it against what you are actually planning to do.
The Grant Only Applies to New
The First Home Owner Grant is $10,000, and it is narrower than most people expect. It applies to a newly built home valued at up to $600,000, or to a land purchase plus a building contract with a combined value up to $750,000. An established apartment or house, however long you have been saving for it, does not attract the grant at all.
In practice that steers the grant towards new stock and towards building, which is a real consideration in Parramatta given how much new supply there is. It is also why the grant and the duty concession do not always land on the same property: one favours new, the other is set by price.
One piece of history worth clearing up, because it still comes up in conversation. First Home Buyer Choice, the option to pay an annual property tax instead of duty, closed to new applicants on 1 July 2023. If you read about it on a page that has not been updated, it is not available to you.
Genuine Savings, and What Counts
Where your deposit is under twenty per cent, most lenders want to see genuine savings: broadly, around five per cent of the purchase price held in your name for about three months. The idea behind it is that a lender wants evidence you can accumulate money, not just that money appeared.
That has consequences for gifts. A parent transferring a lump sum a fortnight before you buy is a real deposit but it is not genuine savings by most policies, and treating the two as the same is a common way to be surprised late. Rent paid consistently can count with some lenders. Policy varies more than you would expect.
The reason to have this conversation early is that three months is a clock. If a small change to where your savings sit turns a decline into an approval, it costs nothing to make that change now and everything to discover it once you have found the place you want.
Schemes, Grants and Duty
Can I really buy with a 5% deposit in Parramatta?
On price, yes, for most of the market here. The Sydney cap on the federal scheme is $1,500,000 and the median unit is around $620,000, so the constraint is rarely the cap.
The constraints that do bite are your borrowing capacity, the genuine savings rule and, on a Parramatta apartment, whether the specific building suits the lender. Those get checked on the actual property rather than assumed.
Do first home buyer loans Parramatta come with lenders mortgage insurance?
Not if you are using the federal guarantee. That is the main thing it does: the government guarantees the portion of the loan that would otherwise have been insured, so the lender does not charge you a premium.
Outside the scheme, a deposit under twenty per cent normally triggers insurance, and it is usually added to the loan rather than paid up front. Whether that is worth it depends on how long the alternative takes you, which is arithmetic we are happy to run.
Can I use the grant and the duty concession together?
Sometimes, and it depends on the property rather than on you. The $10,000 grant only applies to a new home up to $600,000, or land plus a building contract up to $750,000. The duty exemption runs to $800,000 on any first home, new or established.
So a new apartment at $580,000 could attract both. An established house at $780,000 attracts the duty exemption and no grant. We work it out on the address you are considering.
Does a HECS debt stop me getting a loan?
It does not stop you, but it reduces what you can borrow, because the compulsory repayment is treated as a commitment against your income. The higher your salary the more it takes out of your capacity.
Lenders differ in how they treat a balance close to being paid off, which occasionally makes a real difference. It is worth telling us the balance rather than leaving it out.
What is genuine savings and why does my deposit not count?
Genuine savings usually means around five per cent of the price held in your name for about three months. It is evidence that you can accumulate money rather than that money exists.
A gift from family is a real deposit and is welcome, but most lenders will not count it as genuine savings, so a large transfer just before you buy can create a problem where you thought you had solved one. Policy varies between lenders, and there are ways around it.
Who You Will Be Dealing With
One broker, from the first call to settlement. Not a call centre and not a form that goes somewhere else. When you ring back in three weeks with a question about a place you saw on Saturday, you are talking to the person who already knows your numbers.
First purchases run on questions that feel too small to ask. Whether a credit card should be closed, whether a gift will cause trouble, whether an offer at $805,000 on a Parramatta unit is a mistake. Those are the ones worth asking, and there is no cost to asking them.
- Phone (02) 7813 2050
Quickest if you have a property in front of you and a question about it.
- Form Use the enquiry form
Better if you are on site or at work and cannot take a call back.
- Email info@mortgagebrokerparramatta.au
Suits a contract, a floor plan or a loan statement you want read.
Parramatta NSW 2150. Monday to Friday, 9am to 5pm.
Find Out What You Can Buy
Tell us what you earn and what you have saved and we will come back with a Parramatta borrowing figure, the schemes you qualify for and what each of them is worth to you. Twenty minutes, and no commitment attached to any of it.
Where We Work
- Business
- Mortgage Broker Parramatta
- Location
- Parramatta NSW 2150
- Phone
- (02) 7813 2050
- info@mortgagebrokerparramatta.au
- Hours
- Monday to Friday, 9am to 5pm