
C-02 / Family security guarantees
Guarantor Home Loans Parramatta
On guarantor home loans Parramatta your parents are not underwriting your whole loan. They pledge a named slice of equity in their own property, that slice is written into the documents, and their exposure stops there.
That gets missed in both directions. Parents refuse because they believe they are signing for everything, or agree too quickly because they believe they are signing for almost nothing, and the second is the worse mistake of the two. What is worth establishing before anyone signs is exactly where the guarantee stops and what would have to go wrong before it was ever called on.
What Guarantor Home Loans Parramatta Actually Involve
We structure the guarantee: how much needs to be pledged to get you to the deposit a Parramatta purchase needs, which lenders offer a limited guarantee and on what terms, and how the loan is split so the guaranteed portion is identifiable and can be removed later.
The other half of the job is the conversation with the guarantor. They are entitled to understand the commitment in plain terms before signing anything, and they are legally required to get independent advice on it. We would rather explain it fully and have someone decline than have a family sign something half understood.
It is also worth comparing before committing. A guarantee is one of three ways to buy without a full deposit, and the other two do not involve anyone’s parents. We put all three next to each other rather than assuming this is the answer.
How We Put Your Guarantee Together
The order below puts the guarantor’s understanding before the paperwork, which is the opposite of how it often happens.
-
We work out whether you need one
Your income, your savings and what you are trying to buy in Parramatta, against the deposit each route would require. Sometimes the answer is that a guarantee is not necessary, and that is a good outcome for everyone involved.
-
We size the pledge
How much equity has to be guaranteed to get you where you need to be, and no more than that. The guaranteed amount is a number we negotiate with the lender rather than a fixed share, and a smaller pledge is usually available than families assume.
-
Your guarantor gets it explained, then advised
We walk them through what they are committing to, in plain terms, before any document is signed. Then they take it to their own solicitor for independent advice, which the lender requires and which exists for their protection.
-
We lodge and run it to settlement
Two Parramatta properties, two sets of documents and often two conveyancers make this more involved than an ordinary purchase. We coordinate it, and we plan the release of the guarantee at the same time rather than leaving it for later.
Useful to have to hand: your income and savings, a rough idea of what your guarantor’s Parramatta property is worth and what is still owing on it, and whether they are still working. The first conversation needs none of it.
What You and Your Family Ask Us First
What do you need from my guarantor?
Early on, very little: a rough idea of what their property is worth, what is still owing on it, and whether they are still working. That is enough to know whether a guarantee is possible and how large a pledge would be needed.
Later they will need proper documentation and their own solicitor’s advice. Nothing is asked of them formally until they have had the whole thing explained and have decided they want to proceed.
Does any of this cost my parents money?
Not in fees to us. We are paid a commission by the lender when the loan settles, and that applies whether or not a guarantee is involved. Your guarantor will pay their own solicitor for the independent legal advice, which is a modest cost and one worth paying.
If a fee ever applied to your circumstances, it would be set out in writing in our Credit Guide before anyone decided whether to go ahead.
Can you explain this to my parents directly?
Yes, and it is usually the most useful thing we do on these files. Most hesitancy comes from a belief that they would be liable for your entire loan, which is not what a limited guarantee is.
We will also tell them plainly where the risk sits, because a guarantor who agrees without understanding it is a problem for the whole family later. If they decide against it after that conversation, that is a legitimate outcome.
How long does adding a guarantor take?
It adds some time rather than a lot, mostly because there are two properties, two sets of documents and the guarantor’s independent legal advice to fit in. A few extra weeks is a fair expectation.
The step most often underestimated is the solicitor appointment, so it is worth booking that early rather than leaving it until the lender asks.
Why So Many Parramatta Families End Up Here
The arithmetic of this market is the whole reason a family guarantee is a normal conversation rather than an unusual one. Median weekly household income across the Parramatta area is around $2,051, while a median Parramatta house sits at roughly $1.67 million on one measure and higher on others. Saving a twenty per cent deposit against that gap, while renting in the same market, is not a plan that completes in a reasonable time.
Units are a different story and a lot more attainable, which is why plenty of first purchases in Parramatta are apartments. But for a family wanting a house, the deposit is the obstacle rather than the repayments, and the household that can service a loan comfortably is very often the same household that cannot get to the deposit.
A guarantee closes that specific gap. It does not make the loan cheaper, it does not increase what you can borrow, and it is not free money. What it does is let you buy years earlier using equity that is already sitting in the family, and for a lot of households that is the difference between buying and not.
What Your Guarantor Is Actually Committing To
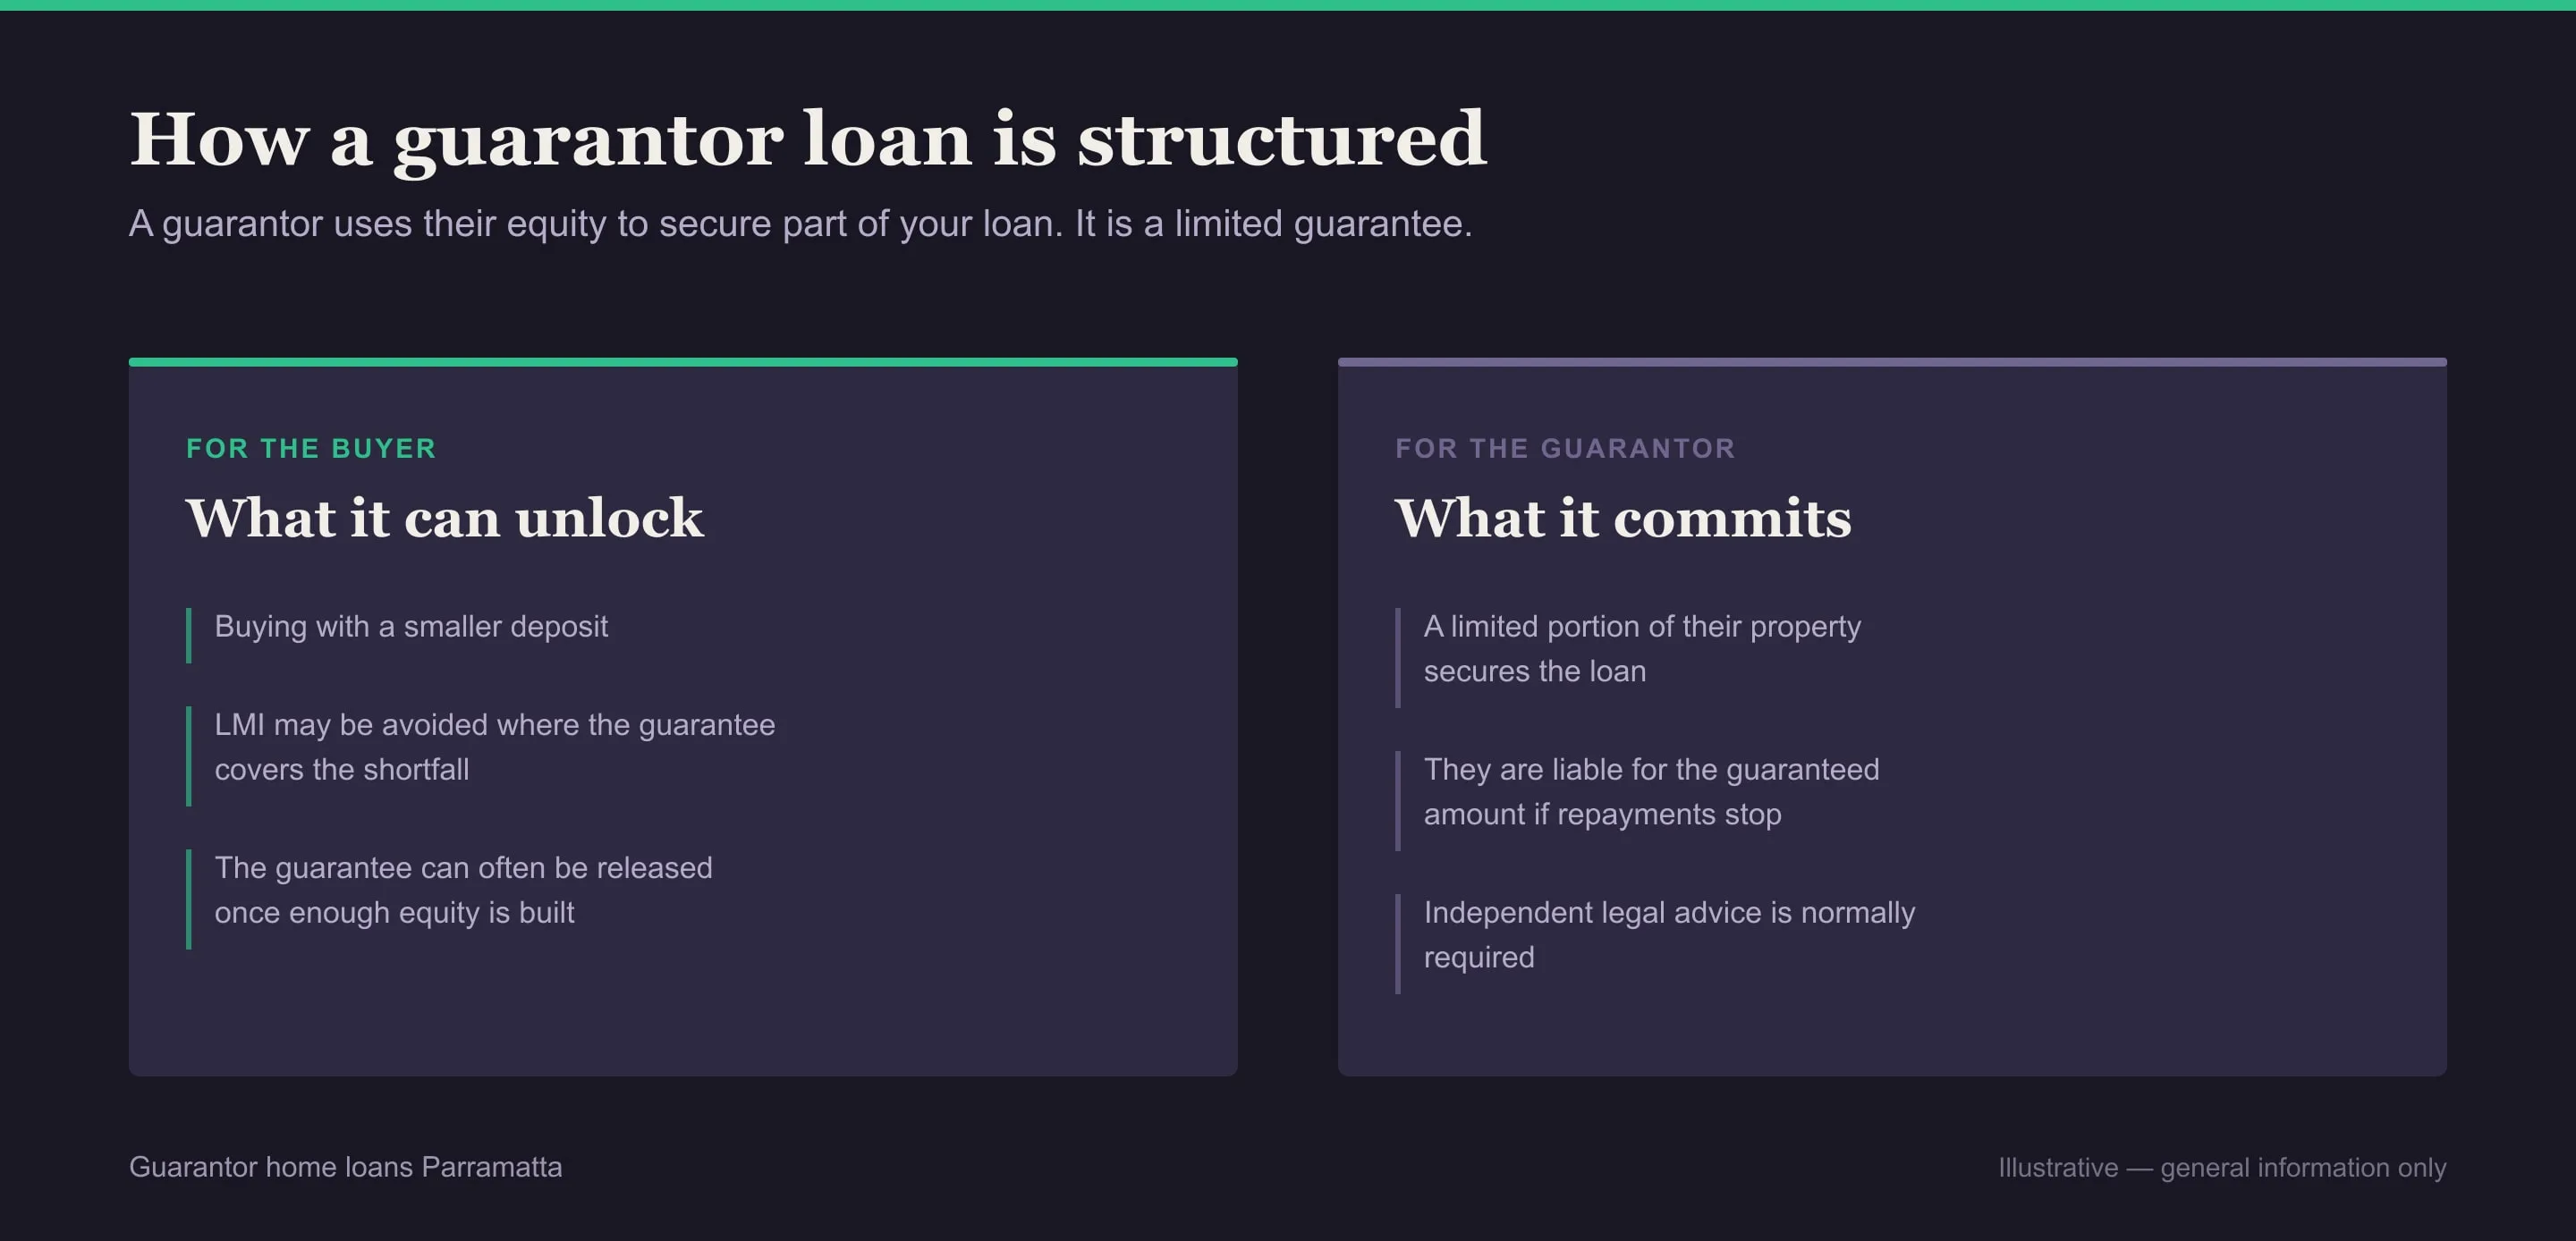
A family security guarantee is limited, and that word carries all the weight. Your guarantor offers a defined portion of the equity in their property as additional security, that amount is specified in the guarantee, and their liability does not extend past it. They are not guaranteeing your whole loan and they are not guaranteeing your repayments in general.
The risk is real and it is worth stating plainly. If the loan defaults and the property sells for less than what is owed, the guaranteed portion can be called on, and that is secured against their home. It is not a formality. It is why independent legal advice is mandatory rather than optional, and why any lender or broker rushing that step should be treated with suspicion.
What we do is make sure the guarantor hears the whole thing from someone willing to talk them out of it. Then they take it to their own solicitor, who advises them without us in the room. That order is deliberate.
Your Guarantor Is Not Committed Forever
This is the part that changes the answer for most hesitant parents, and it comes up too late in most conversations. The guarantee can be released once you hold enough equity in your own Parramatta property, typically around twenty per cent, at which point your parents’ property comes off the security entirely and they are free of it.
Two things get you there: paying the loan down, and the property increasing in value. Either counts, and both usually happen at once. It requires a valuation and a formal application to the lender rather than happening automatically, so it needs to be asked for.
Planning the exit at the start is worth doing. We work out what the release would look like on a realistic Parramatta timeline, so the guarantor is agreeing to a defined period rather than to an open-ended commitment. A five year obligation with a clear end is a very different proposition to one with no visible finish.
Guarantee, Insurance or the Federal Scheme
There are three ways to buy without a full deposit and they are not interchangeable. A guarantee uses family equity and can avoid mortgage insurance entirely. Lenders mortgage insurance costs you a premium, usually added to the loan, and involves nobody else. The federal 5% Deposit Scheme guarantees part of the loan through government and also avoids the insurance premium, but it comes with eligibility rules and a narrower field of participating lenders.
The right one depends on your circumstances and on how your family feels about the risk. If you qualify for the federal scheme and are buying within its price cap you may not need to involve your parents at all, which is the better outcome where it is available.
One thing applies whichever route you take: a guarantee does not change what you can afford. Your borrowing capacity is still assessed on your income against your total debt, and the debt-to-income limits still apply. A guarantee solves a deposit problem. It does not solve a serviceability problem, and anyone suggesting otherwise is misleading you.
How a Guarantee Actually Works
Is my guarantor liable for my whole loan?
No, not with a limited guarantee, which is the standard structure. They guarantee a specified portion, that figure is written into the documents, and their liability does not go beyond it.
The old style of unlimited guarantee, where a parent stood behind the entire debt, is not what is being offered here. If anyone presents you with one, that is worth a second opinion.
What happens to my parents if I lose my job?
Missing a repayment does not trigger anything against the guarantor by itself. The guarantee is security rather than a payment obligation, so the first step is always a conversation with the lender about hardship arrangements.
The guaranteed portion only comes into play if the loan defaults and the property is sold for less than the outstanding debt. It is a real risk and it should be understood as one, but it sits at the end of a long process, not at the first missed payment.
When can the guarantee be removed?
Generally once you hold around twenty per cent equity in your own property, through a combination of paying the loan down and the property rising in value.
It is not automatic. It requires a valuation and a formal application to the lender, so somebody has to ask for it. We plan that release at the start so your guarantor knows roughly how long they are committing to.
Can my parents guarantee if they still have a mortgage?
Often yes. What matters is the equity available in their property rather than whether the mortgage is fully repaid, so a home with substantial equity and a remaining loan can still work.
Their own position gets looked at as part of it, including their income and whether they are retired, and lenders differ on how they treat guarantors on a pension. It is worth asking rather than assuming they are ineligible.
Do guarantor home loans Parramatta let me borrow more?
No, and this is the most important misunderstanding to clear up. A guarantee solves a deposit problem. Your borrowing capacity is still assessed on your income against your total debt, and the debt-to-income limits apply exactly as they would otherwise.
So if the constraint is what you can service rather than what you have saved, a guarantee will not move it. We check serviceability before anyone approaches a family member, because there is no sense having that conversation if the loan was never going to pass.
Who Talks Your Family Through It
The same broker speaks to you and to your guarantor, wherever in Parramatta they live. That matters more here than on any other file, because two people are committing to one transaction and they need to be hearing the same explanation rather than two versions of it.
We are happy to do that conversation with everyone in the room, or with your parents on their own if they would rather ask their questions without you there. Both happen, and the second one is often more useful.
- Phone (02) 7813 2050
Quickest if you have a property in front of you and a question about it.
- Form Use the enquiry form
Better if you are on site or at work and cannot take a call back.
- Email info@mortgagebrokerparramatta.au
Suits a contract, a floor plan or a loan statement you want read.
Parramatta NSW 2150. Monday to Friday, 9am to 5pm.
Work Out Whether You Need One
Tell us what you earn and what you have saved and we will put a guarantee, mortgage insurance and the federal scheme side by side against Parramatta prices, with what each would cost you and what each would ask of your family. Sometimes the answer is that nobody needs to be involved.
Where We Work
- Business
- Mortgage Broker Parramatta
- Location
- Parramatta NSW 2150
- Phone
- (02) 7813 2050
- info@mortgagebrokerparramatta.au
- Hours
- Monday to Friday, 9am to 5pm